Dec–Mar
Winter
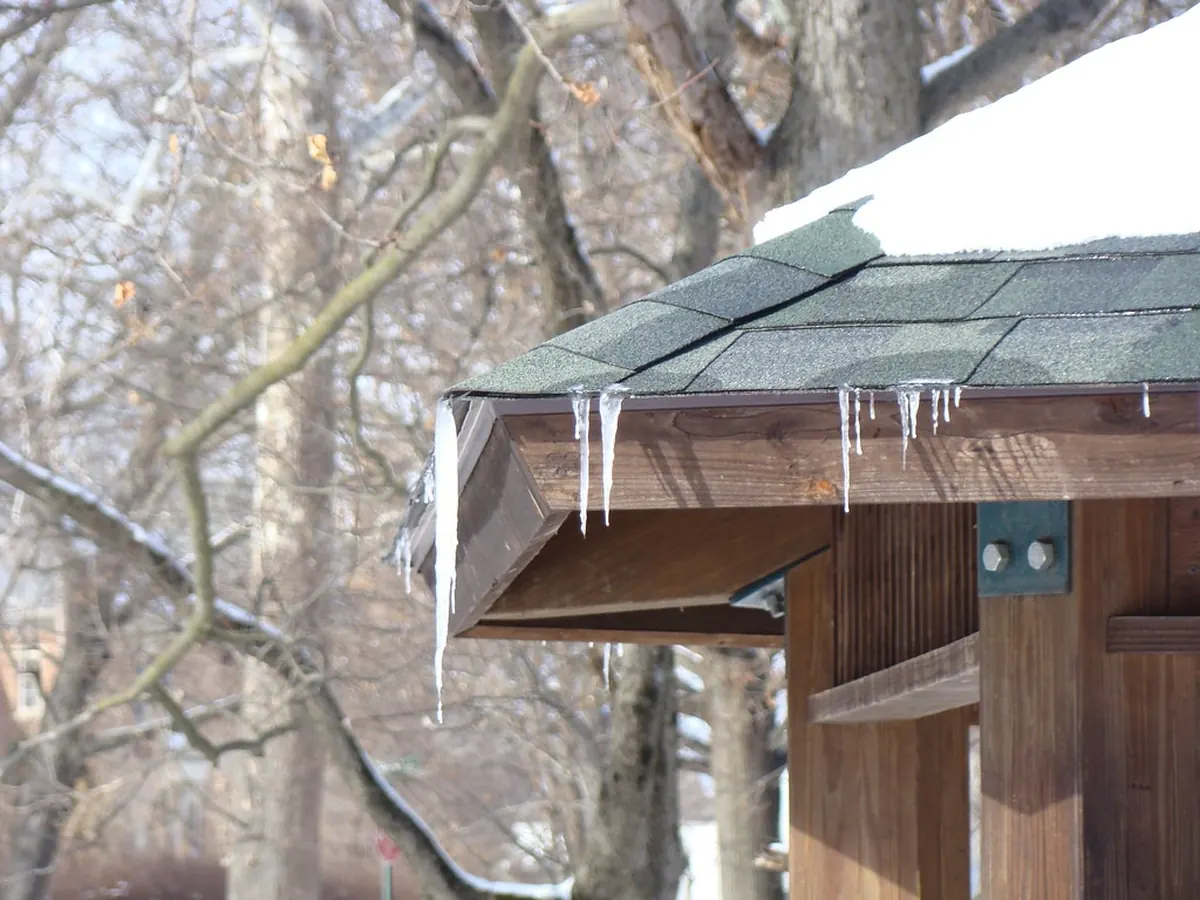
Most Maine claim files open in the cold months, and many of them stay open until the snow comes off the roof.
- Ice dams behind gutters
- Snow load on flat and low roofs
- Frozen pipes at closed camps
- Chimney and wood-stove fires
Statewide · All 16 counties · Islands included
Your insurer accepted the claim, but the check won’t rebuild the roof, the ceiling or the camp. Maine Insurance Appraiser prices the loss line by line and takes it through the appraisal process written into your policy.
Why owners call
Most disputed Maine claims aren’t denials. They’re short: an attic that was never opened, a slope left off the roof report, ice-barrier membrane priced for one course when the eave needs three, clapboard that can’t be matched. A Maine Insurance Appraiser exists for the distance between the carrier’s number and the real cost to put the building back.
We build our own scope from the inspection, not from an edited copy of the carrier’s estimate, and we price what we can defend in front of an umpire.
Appraisal work
Start with a review of the carrier’s estimate, or bring us in after appraisal has been demanded. Every service rests on the same thing: an independent, defensible number for your loss.
 01
 02
 03
 04
 05
 06
 07
 08
 09
 10
 11
 12
The Maine claim year
Weather here runs on a calendar. So do claims. Tap or hover a season to open it.
Dec–Mar
Most Maine claim files open in the cold months, and many of them stay open until the snow comes off the roof.
Apr–May
Thaw shows what winter hid. The roof that looked fine in February often shows the damage in April.
Jun–Aug
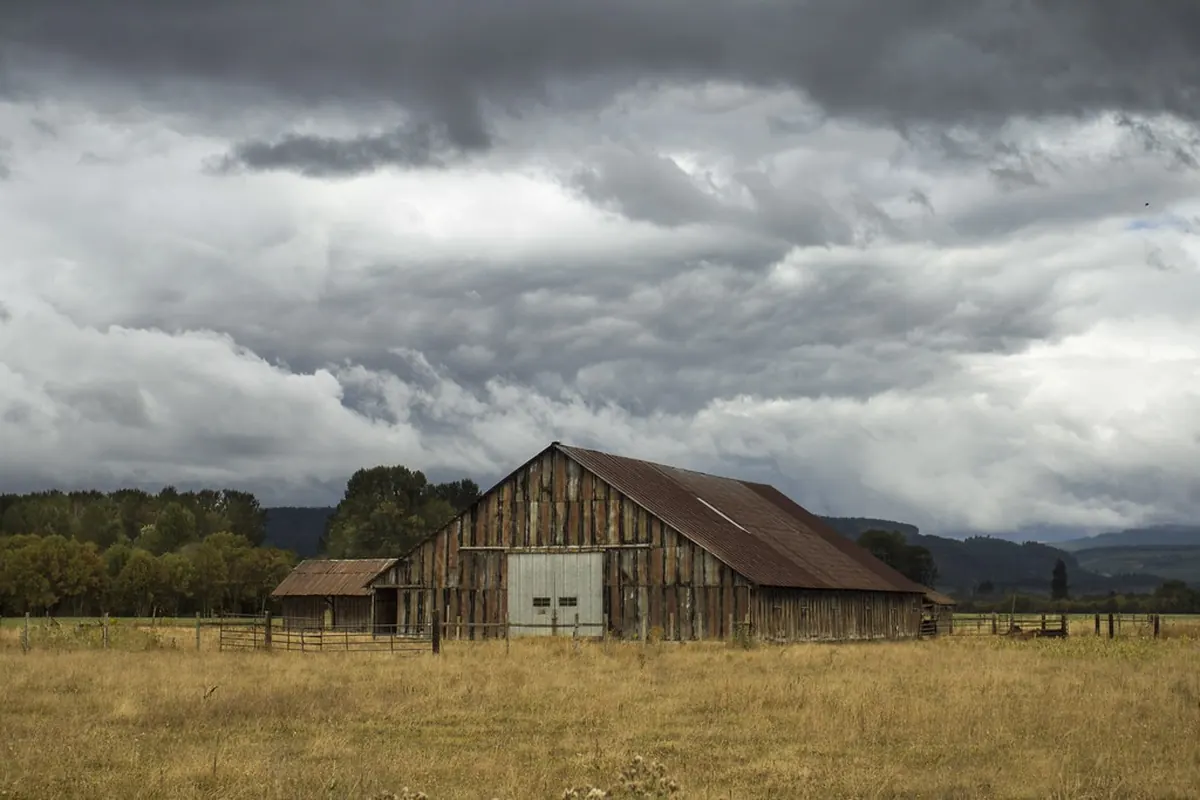
Short, violent storms track across the interior and drop hardwoods and pines onto houses and camps.
Sep–Nov
Coastal storms and the remnants of tropical systems test siding, windows and shingles from Kittery to Eastport.
How it moves
The appraisal condition turns an open-ended argument into a defined process with an end. Here’s how Maine Insurance Appraiser carries a file through it.
We read your policy’s appraisal condition, the carrier’s full estimate and your photos, then tell you whether appraisal fits or another path is cheaper.
On-site inspection and measurements, including the attic and the areas winter hides, and a line-item estimate priced for your part of Maine.
Appraisal is demanded in writing and Maine Insurance Appraiser is named as your appraiser within the time your policy allows.
We work through each disputed line with the carrier’s appraiser. Many disagreements narrow sharply at this stage.
Items still in dispute go to a neutral umpire. Once two of the three sign, the amount of loss is set and payment follows under your policy.
Two numbers, one minute
Type the carrier’s estimate and your contractor’s. If the gap is wide, a call with a Maine Insurance Appraiser makes sense. If it’s narrow, a documented supplement may close it faster and for less.
The full settlement gap projector adds fees and shows the net at three possible award levels.
Coast to County
A Kennebunk beach cottage, a Lewiston triple-decker and a Presque Isle potato house don’t share a price list. Swipe through the regions.
York County
Kittery to Old Orchard Beach: beach cottages, brick mill conversions in Biddeford and Sanford, and condominiums in every town.
Cumberland County
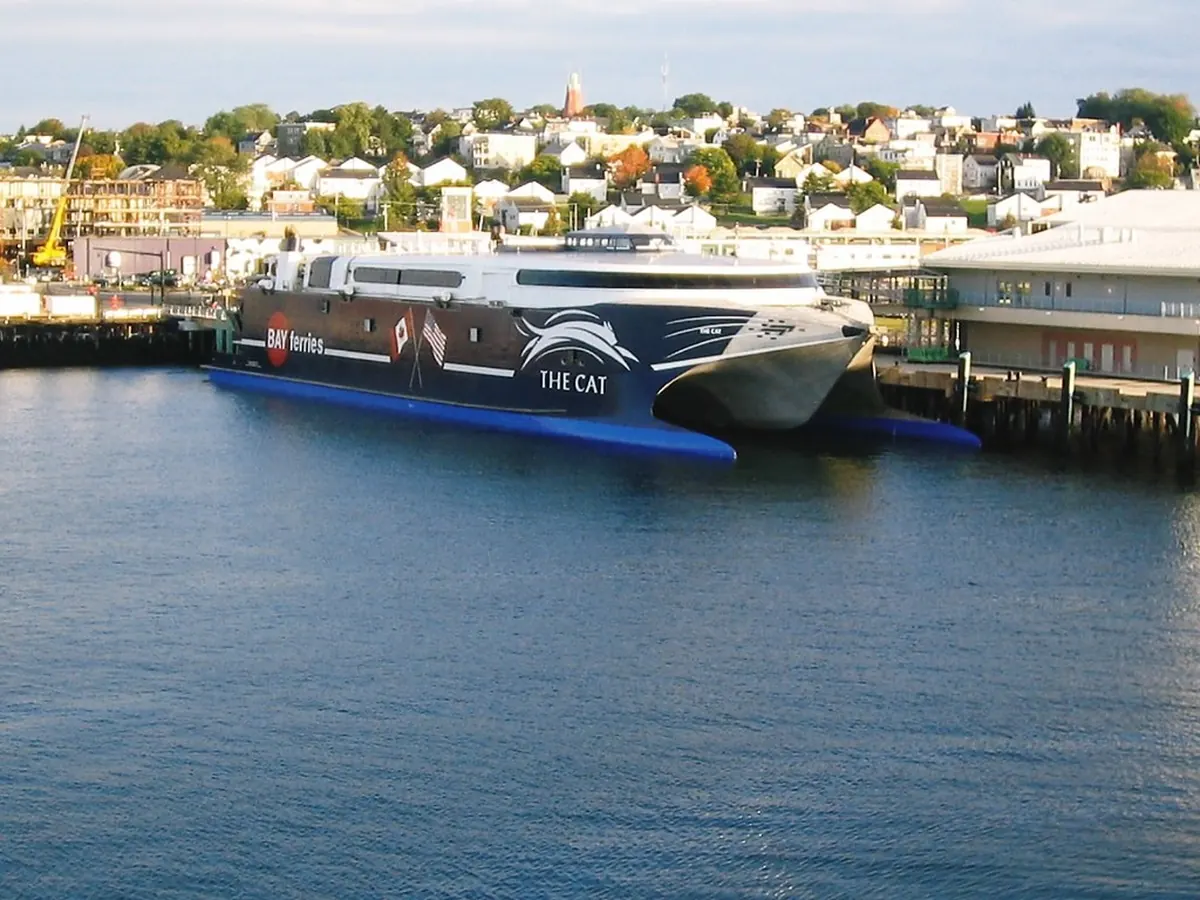
Victorian brick, triple-deckers, waterfront commercial and island homes that need a ferry before the first shingle arrives.
Sagadahoc · Lincoln · Knox · Waldo
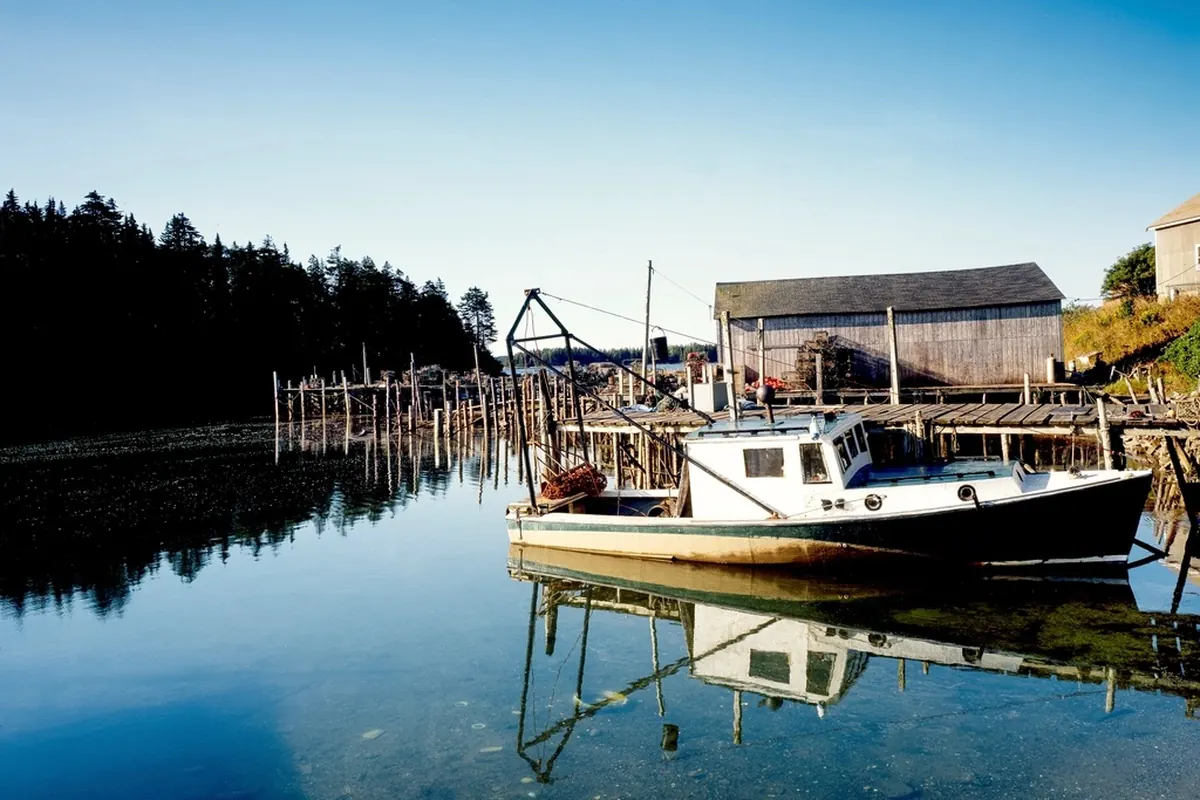
Bath to Belfast: shipbuilding towns, harbors, capes and connected farmhouses, plus island homes off Rockland and Boothbay.
Hancock · Washington
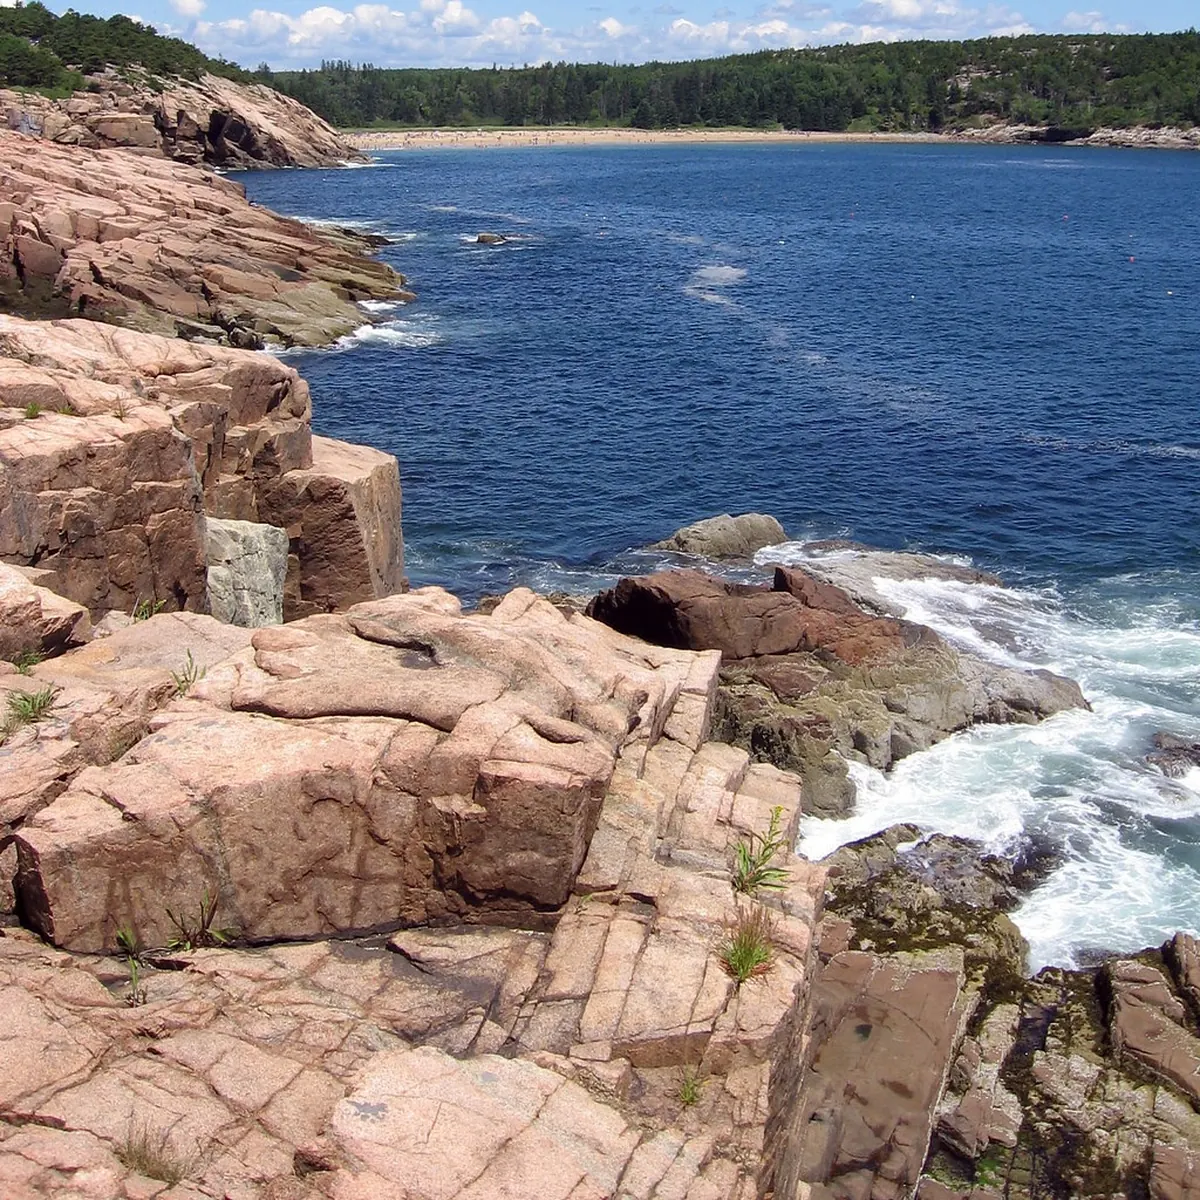
Mount Desert Island inns and cottages, blueberry barrens and fishing towns where contractors travel long distances.
Kennebec · Androscoggin · Franklin · Oxford · Somerset
Augusta, Lewiston and Waterville mill cities, lake camps, and ski-area condominiums under heavy snow at Sugarloaf and Sunday River.
Penobscot · Piscataquis · Aroostook
Bangor’s Victorian neighborhoods, Moosehead camps and Aroostook farms with potato houses and metal outbuildings.
Claim math
Work through the numbers before you call. Every tool runs in your browser and nothing you type is stored or sent.
 Estimator
 Calculator
 CalculatorCalculator
 Planner
 Checklist
 Checker
Storm record
Adjusters and contractors still measure big events against these. A Maine Insurance Appraiser has to know what each one did to roofs, rivers and price lists.
Wildfires burned across Mount Desert Island and southern York County, reshaping Bar Harbor.
A storm surge pushed up the Penobscot and flooded downtown Bangor.
Set Portland’s tide record, 14.17 feet, which stood for 46 years.
Ice-coated forests and power lines; parts of central and southern Maine were dark for weeks.
A record number of Maine customers lost power as trees came down on roofs and wires.
Wind and heavy rain on snow sent the Kennebec and Androscoggin over their banks.
A new Portland tide record of 14.57 feet; wharves, fishing shacks and beach homes damaged.
Where we work
We inspect in every county. These are the places we’re called most often.
Fit check
Maine Insurance Appraiser will tell you on the first call if your claim belongs somewhere else.
Answers
Short answers about the process, the cost and when appraisal is the wrong move.
We value the damage when you and your insurer agree the loss is covered but disagree on what it costs. As your named appraiser we inspect, write an independent line-item estimate, reconcile it with the carrier’s appraiser and, if needed, present the open items to an umpire.
No. A public adjuster handles and negotiates the whole claim. An appraiser works inside the policy’s appraisal condition on one question, the amount of loss, and doesn’t give legal advice.
When coverage is accepted, you have the carrier’s itemized estimate, and the gap between it and a contractor’s itemized number is meaningful, often more than about 10% or several thousand dollars.
Usually not. Appraisal sets the amount of a covered loss. Coverage denials and claims-handling complaints belong with a Maine attorney or the Bureau of Insurance.
Each side pays its own appraiser and usually half the umpire. We put our fee in writing before work starts, and the first conversation is free.
Yes. We work in all 16 counties, including island properties reached by ferry and farms in Aroostook. Remote access is planned into the inspection, not avoided.
Owner guides
Practical guides from Maine Insurance Appraiser on winter claims, policy wording and documentation.
Ice dam claims in Maine tend to grow after the first inspection. Here is where estimates fall short and how to build a file that shows the full damage.
A plain-language walk through the appraisal clause found in most Maine property policies, with the questions to ask at each sentence.
Seasonal camp freeze claims often turn on vacancy and heat conditions before the amount of loss is ever discussed. Here is how to read those terms and document the loss.
Before you sign the release
Start here
Tell us what happened and what the carrier offered. We’ll review it and give you a straight answer on whether appraisal is worth pursuing. No pressure and no obligation.